
Since I’m never really one to go with the flow, today I’ll hold true and bludgeon the sacred cow of all financial advice gurus—the IRA and the 401k. It’s not that I’m trying to be controversial or contrary to spite Dave and Suze.
That’s just an added bonus.
I am concerned about the conventional wisdom that says the IRA (both traditional and Roth) and the 401k are the best ways to save for retirement. In fact, these sorts of qualified plans could trap you and really put a squeeze on your retirement plans.
A short story to illustrate my point
There once was a guy who worked for XYZ Manufacturing. He’d worked there for 35 years, and at the ripe old age of 58, he was eligible to retire and decided it was time to cash in his chips.
His company had a tax-qualified plan (the type is irrelevant for our purposes) to which he had contributed for the past 35 years.
So, he retired and rolled over his $900,00 balance to an IRA.
At the time, it seemed like a healthy sum.
Right after retiring, he sold his house in the expensive suburb where he’d raised his family. He and his wife packed up and moved to their cottage situated in an idyllic little community in the Adirondacks to live happily ever after.
For two years, things were going well. He had managed to pocket a nice chunk from the sale of his house, and they had lived comfortably on that money.
Now, we get to the dark part of the story.
At 60, he’s out of money from the sale of the house. The only liquid assets he has left are the $900,000 in his IRA, another $75,000 in his wife’s Roth IRA, and about $20,000 in a savings account.
Everything still seems okay, right?
Except for one thing…
For two years, he’d been living on money that wasn’t taxable. Remember that he’d lived in his primary residence for a long time—henceforth, no capital gains.
He parked that money in an interest-bearing checking account. Yeah, he paid taxes on what little interest that money earned, but keep in mind that it was an ever-decreasing amount, and interest rates on interest-bearing checking accounts usually don’t cause much of a tax burden.
He needs to draw about $75,000 a year to maintain their lifestyle.
We’re not talking about 14-day cruises through the Mediterranean—just everyday expenses like property taxes, insurance, prescriptions, etc.
Every bit of money he has is taxable.
Okay, not every bit…they could tap the Roth IRA…except that his wife is only 57. They’ll be hit with a 10% penalty for early withdrawals. Even still, it’s only enough for one year.
If he wants to generate $75,000 in net spendable income, how much will he have to withdraw to accomplish this?
I won’t get into tax rates and deductions and all that, but suffice it to say, he has to “gross up” the amount by a lot to net $75,000. And remember, with every withdrawal, he’s depleting his resources.
You can imagine the rest of the story.
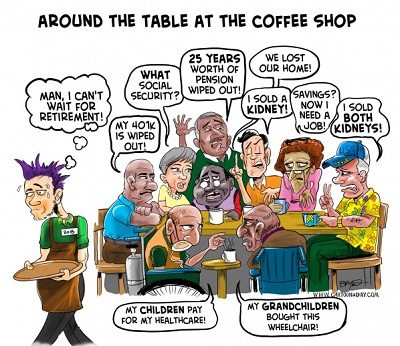
He really only has two options:
- Hope he can find a new job to at least supplement the income
- Significantly downgrade their lifestyle
Neither option is very desirable and certainly not what they had in mind.
The Moral of the IRA/401k/Tax Qualified Money Story
Be careful as to what extent your net worth will be subject to income taxes down the road. The idea of deferring income taxes now seems like a great idea, but don’t be lulled into thinking you’ll be home free forever if you do it.
Of course, we believe that cash value life insurance can be a tremendous tool to accumulate and distribute money at retirement. That’s no big surprise, I’m sure.
I won’t say it’s the only or even the best solution for your particular situation, but it’s probably worth a look if the story I illustrated above sends a chill up your spine.
We’re always happy to guide you through some scenarios. We will give you all the information you need to determine if cash value life insurance works for you and ensure that your 401k and IRA are doing what they’re supposed to.
Could not agree more. My parents are approaching retirement and are constantly keeping non-taxable money very close by for this exact reason!
I agree entirely that tax diversification is essential. The story has a glaring flaw though — there’s no way that $900k is going to produce $75k lifetime income, even if it were entirely non-taxable.
Hi Jim–you are absolutely right, and I probably didn’t communicate that effectively. That is a big takeaway from this story, the guy I discuss in the post has little to no hope of achieving a $75,000 income from a $900,000 nest egg. That sort of withdrawal is not sustainable.